Long-Term Care Insurance Is Not Just for Nursing Homes
A long-term care insurance policy may sit in a filing cabinet for years while the person who owns it begins paying privately for help at home.
The family may assume the policy is meant for a future nursing home stay. Meanwhile, an older parent needs help bathing, getting dressed, preparing meals, or staying safely engaged in familiar routines.
That assumption can be costly. Some long-term care insurance policies cover eligible care delivered in the person’s own home, including assistance with everyday activities and supervision related to cognitive impairment. The policy does not necessarily require someone to move into a facility before benefits can be used.
The important word, however, is some. Coverage, eligibility rules, waiting periods, provider requirements, and payment methods vary by policy. Families should understand the contract before building a care plan around it.
What Is Long-Term Care Insurance Designed to Pay For?
Long-term care insurance is generally designed for ongoing assistance that health insurance and Medicare often do not cover. This is usually support with daily living rather than short-term treatment for an illness or injury.
Medicare distinguishes long-term or “custodial” care from qualifying skilled home health services. It generally does not pay for ongoing nonmedical help when that is the only care a person needs. Private long-term care insurance may help fill that gap, depending on the policy.
Home-based benefits may include services such as:
Assistance with bathing, dressing, toileting, eating, or transferring
Supervision for a person with qualifying cognitive impairment
Help from a home care aide
Homemaker or meal-support services
Respite care that gives a family caregiver time away
Care coordination or other home-based services specifically named in the policy
Not every policy includes every service. Older policies may define home care differently from newer ones, and some contracts impose specific requirements on the agency or caregiver providing the service.
Why Families Often Miss the Home-Care Benefit
The phrase “long-term care” is commonly associated with nursing homes. That can lead families to overlook a policy during the earlier period when a parent still wants to live at home but needs regular assistance.
Other families know the policy exists but assume they should save it for a later stage. That decision may or may not make financial sense. Benefits are usually limited by a daily or monthly maximum, a total benefit pool, a benefit period, or some combination of these.
Whether to begin a claim depends on the person’s needs and the policy’s design.
The best first step is not to guess. It is to find the complete policy and ask the insurer how home-care benefits work under that specific contract.
A Diagnosis Alone May Not Activate Benefits
One of the most important things families should know is that needing help and qualifying for insurance benefits are not always the same.
Many tax-qualified long-term care policies use functional or cognitive “benefit triggers.” A common functional trigger is the inability to perform at least two activities of daily living without substantial assistance for an expected period of at least 90 days.
These activities commonly include:
Bathing
Dressing
Eating
Toileting
Transferring
Continence
A separate trigger may apply when a person requires substantial supervision because of severe cognitive impairment.
The policy may require an assessment or certification from a licensed healthcare practitioner. It may also require a written plan of care. A diagnosis such as Parkinson’s disease, stroke, or dementia can be clinically important without, by itself, satisfying the contract’s benefit trigger.
This is one place where a physician-informed approach can add value. A careful assessment should connect the person’s health condition to what is happening during the day: which activities require assistance, how often help is needed, and whether a new decline should receive further medical evaluation.
The Waiting Period Can Change the Family’s Budget
Even after a claim is approved, benefits may not begin immediately. Many policies include an elimination period, which functions like a waiting period before the insurer starts paying.
The policy may count:
Calendar days: Each day that passes after eligibility begins may count.
Service days: Only days on which the person receives qualifying paid care may count.
This distinction matters. A 90-day elimination period based on service days can take much longer than 90 calendar days to complete if care is scheduled only a few days each week.
Families should ask:
Who pays during the elimination period?
Which services count toward it?
Does care provided by relatives count?
What documentation must be submitted?
Does each day count, or only days when paid care is received?
How the Policy Pays Matters Too
The presence of a home-care benefit does not tell you how payment will work. Policies generally use one of several approaches:
Reimbursement: The insurer reimburses eligible expenses up to the policy limit after receiving invoices or proof of service.
Indemnity: The policy pays a set amount once benefit requirements are met, subject to the contract.
Cash benefit: Some policies provide a cash amount with greater flexibility in how care is arranged.
Families should also confirm whether payment goes to the policyholder, an authorized representative, or the care provider.
“Covered” does not always mean the insurer will pay the home care agency directly.
The Provider May Need to Meet Policy Requirements
Some policies require home care to be provided by a licensed agency. Others may specify caregiver qualifications, exclude care provided by certain relatives, or require services to follow an approved plan of care.
Before selecting care, ask the insurer:
Does this policy include home-care benefits?
Which services are eligible?
What benefit trigger must be met?
Is an assessment or healthcare practitioner’s certification required?
How is the elimination period counted?
Must the provider be licensed or meet other qualifications?
What documents are required with each claim?
Is the benefit paid by reimbursement, indemnity, or cash?
What are the daily or monthly limit and remaining total benefit?
Who receives payment?
Ask for the answers in writing whenever possible. Record the date of each call, the representative’s name, and any claim or reference number.
What Home Care Might Look Like Once Benefits Begin
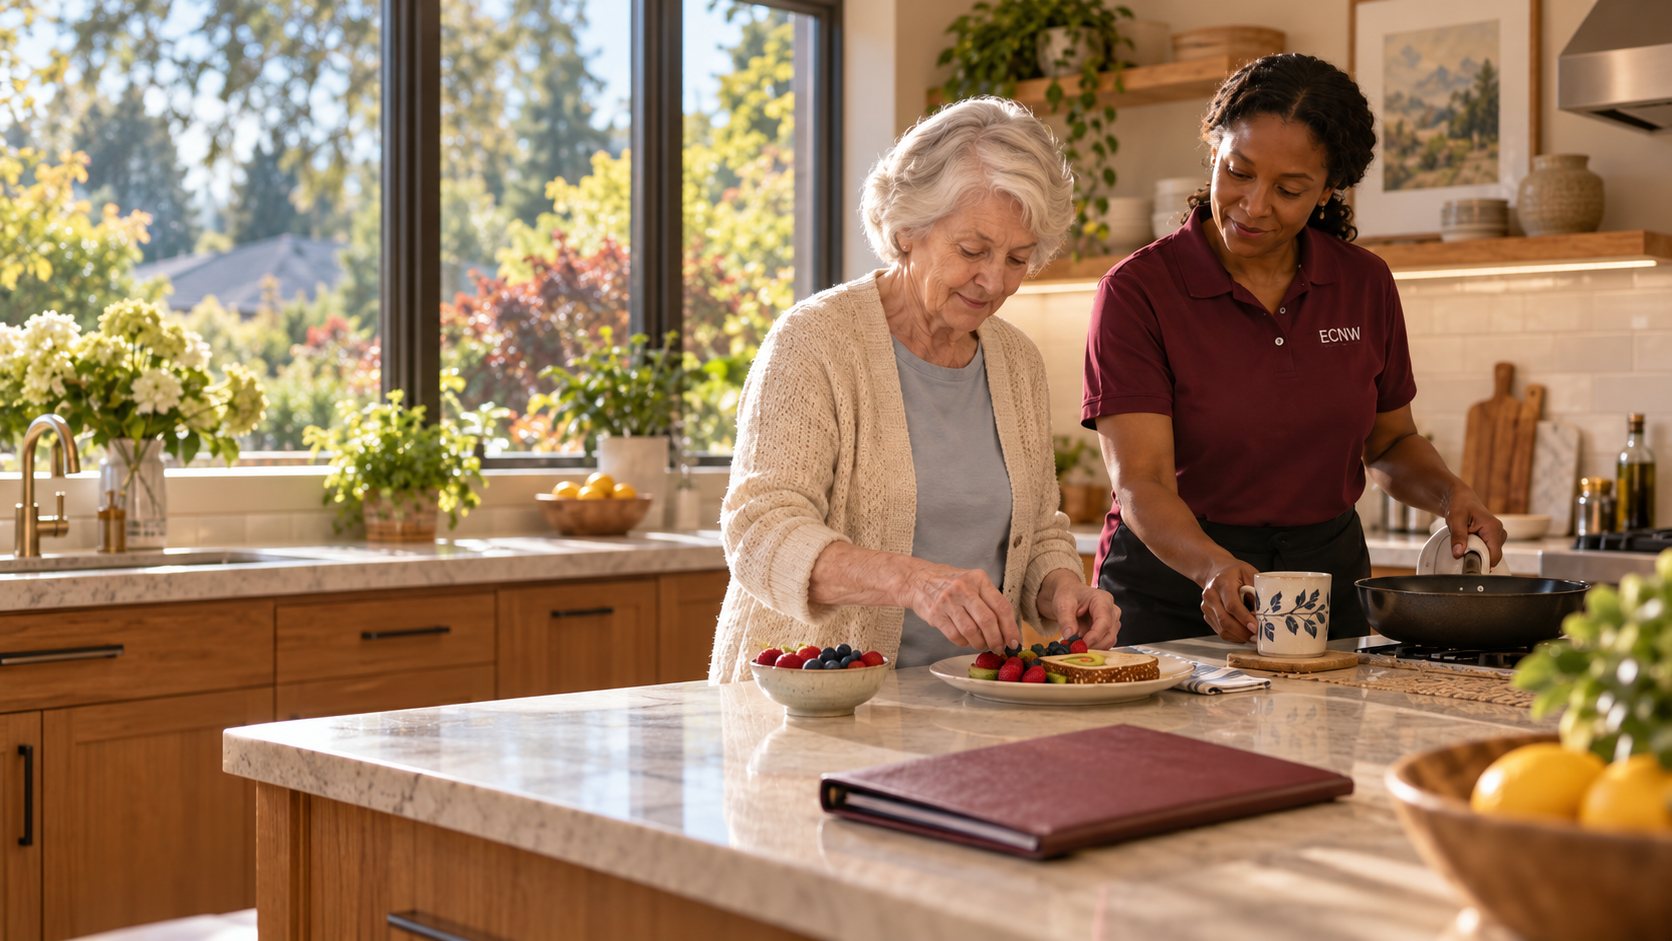
Using long-term care insurance does not automatically mean beginning around-the-clock care.
A home-care plan might start with help during the most difficult part of the day. For example, a caregiver could assist with morning bathing and dressing, prepare lunch, provide medication reminders within the caregiver’s permitted role, or stay with a person who should not be left alone because of cognitive changes.
The schedule should reflect the person’s assessed needs and the insurer-approved plan while preserving the abilities and choices the older adult still has.
Families may explore Home Care Aides for personal and daily-living support, Dementia and Memory Care when supervision and consistent routines are important, or Respite Care when relatives are providing much of the care themselves.
Five Steps to Take Before Care Becomes Urgent
1. Locate the complete policy
Look for the policy contract, declarations or schedule of benefits, amendments, and recent statements. A marketing brochure is not enough to determine coverage.
2. Call the claims department
Ask specifically about opening a home-care claim. The claims department may provide different and more detailed information than a general customer-service or sales representative.
3. Request the claim packet
Review the assessment, certification, plan-of-care, provider, invoice, and authorization requirements before services begin when possible.
4. Gather evidence of daily needs
Document the activities that require help, when difficulties occur, and what assistance family members are already providing.
Focus on observable function rather than general statements such as “Dad is slowing down.”
5. Coordinate the care and documentation
Choose a provider that can supply the records the policy requires. Keep copies of care plans, schedules, invoices, assessments, insurer correspondence, and explanations of benefits.
Is Long-Term Care Insurance the Same as Medicare?
No.
Medicare is health insurance with limited coverage for qualifying skilled home health care. It generally does not cover ongoing custodial assistance such as bathing, dressing, meal preparation, or supervision when those are the only services needed.
Long-term care insurance is a separate private policy intended to address some extended-support needs.
Families should not assume that Medicare’s denial of a service means an LTC policy will also deny it. They also should not assume that Medicare approval automatically establishes LTC insurance eligibility. Each program applies its own rules.
When Should a Family Check the Policy?
Check it before the situation feels like a crisis.
Useful moments include:
When an older adult begins receiving regular help from family
After a significant health change
During discharge planning
When memory changes begin affecting safety
Before hiring ongoing home care
When family caregivers are becoming exhausted
Starting early creates time to understand the elimination period, arrange an assessment, select an eligible provider, and prepare for expenses that may occur before benefits begin.
For Seattle and King County families, the Washington State Office of the Insurance Commissioner offers consumer information about long-term care insurance. The insurer, however, remains the source of the final coverage decision for an individual policy.
Turn an Old Policy Into a Current Care Conversation
A long-term care policy should not remain unopened simply because no one is considering a nursing home.
If an older adult needs ongoing help at home, the family can ask whether the policy was designed for this stage: enough assistance to make daily life safer and more manageable while preserving familiar routines and personal choice.
Elite Care Northwest can help families think through home-care needs and the documentation that may support care planning. Coverage, eligibility, reimbursement, and payment arrangements must be confirmed directly with the insurer.
To discuss the support your family is considering, Schedule a Consultation.
This article provides general educational information and is not insurance, legal, tax, or financial advice. Policy terms and claim decisions vary. Consult your insurer and appropriate professional advisers regarding your circumstances.